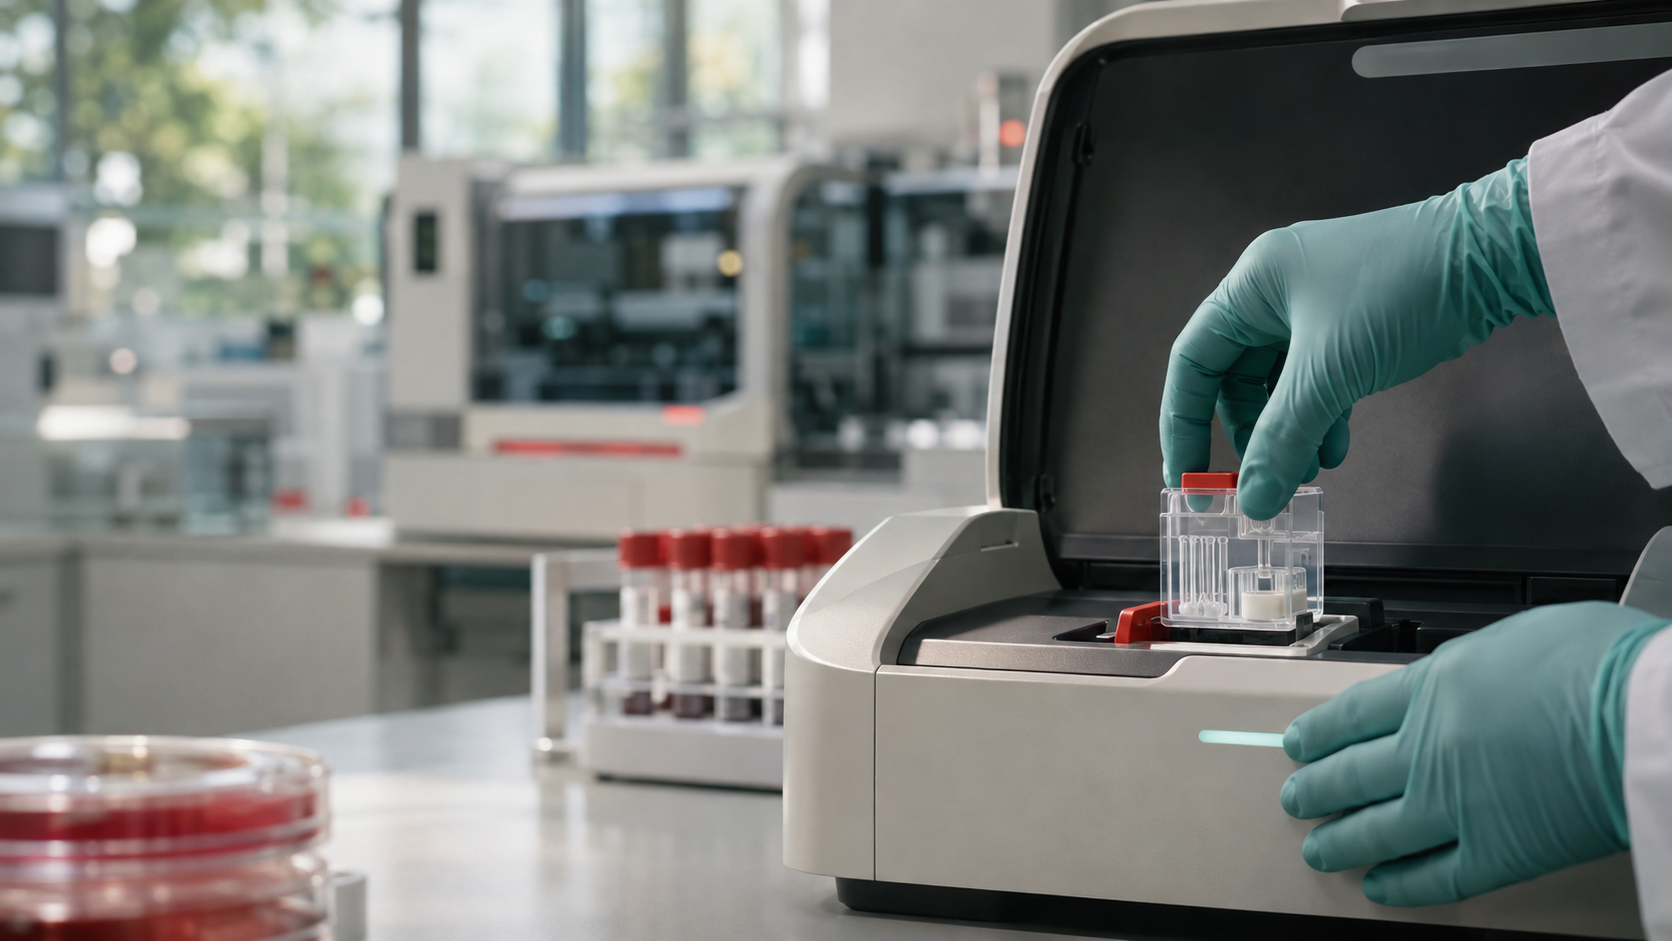
The market watches the respiratory season. The deeper value lies in the installed base, recurring reagent sales and the expansion of diagnostics closer to the patient.
MITUXA — Investment Thesis | 6 November 2026
Investment Snapshot
| Item | MITUXA view |
|---|---|
| Company | bioMérieux |
| Ticker | BIM — Euronext Paris |
| Reference price | €92.30 |
| Estimated market capitalisation | €10.9bn |
| Horizon | 3–5 years |
| Business quality | High |
| Balance sheet | Strong — €236m net cash at 30 June 2026 |
| Risk | Medium |
| Conviction | 7/10 |
| Decision | Positive watchlist; accumulate below €85 |
The instrument matters less than what it will consume
At first glance, bioMérieux looks like a diagnostic equipment manufacturer whose results depend on flu seasons. When respiratory infections circulate more widely, testing volumes rise. When epidemiology weakens, revenue disappoints and the market cuts its estimates.
That interpretation is not wrong. It is incomplete.
bioMérieux’s most important economic asset is not the instrument sold today. It is the sequence of tests that instrument may run over many years. Once a platform is installed in a hospital, laboratory or clinic, it becomes an entry point for recurring revenue from reagents, consumables, software and services.
In 2025, bioMérieux generated €4.07bn of revenue. Reagent sales contributed €3.39bn, approximately 83% of the total, while equipment sales represented only €282m. That difference captures the investment case: the company installs infrastructure and then monetises its use.
Customers do not change suppliers easily. Replacing a platform can require test validation, staff training, revised laboratory workflows and changes to information systems. These switching costs do not appear on the balance sheet, but they form a genuine competitive barrier.
The decisive question is therefore not simply how many instruments bioMérieux sells. Investors need to ask how many are installed, how frequently they are used, which additional panels they can run and how much recurring revenue each system can generate.
The central MITUXA idea: bioMérieux should be analysed as a recurring diagnostic platform, not as a cyclical respiratory-testing manufacturer.
Instrument placement → clinical integration → reagent consumption → additional panels → higher utilisation → greater switching costs
Four ecosystems, one underlying logic
bioMérieux does not rely on one growth engine. It has four, each with a different market profile but the same underlying mechanism: install a technology, expand its menu and increase its utilisation.
1. BIOFIRE: finding several pathogens in a single test
BIOFIRE is the group’s main syndromic molecular-diagnostics franchise. Instead of testing separately for multiple bacteria and viruses, a panel searches simultaneously for numerous pathogens from one patient sample. Clinicians receive an answer quickly and can make an earlier treatment decision.
The franchise remains exposed to respiratory panels, but its non-respiratory applications matter more to long-term value: gastrointestinal infections, meningitis, encephalitis, pneumonia and bloodstream infections.
In 2025, non-respiratory BIOFIRE panels generated €598m, with organic growth of 10%. The installed base increased by a net 1,800 instruments, compared with 1,350 in the previous year. Each placement expands the commercial surface available for future reagent sales.
2. SPOTFIRE: moving diagnostics closer to the patient
SPOTFIRE brings syndromic molecular testing to clinics, emergency departments, physician offices and other settings where a result is needed during the patient visit.
The installed base reached 6,400 instruments at the end of 2025 and exceeded 7,200 by June 2026. More than 900 additional systems were installed during the third quarter. The pace of expansion is impressive. The next test is whether utilisation and reagent revenue follow those placements.
US clearance of the SPOTFIRE Vaginitis Panel is strategically important. It moves the platform into women’s health and adds a use case that is less dependent on respiratory epidemiology. The broader the menu becomes, the stronger the economics of each installed instrument should become.
3. Clinical microbiology: the less visible engine
Clinical microbiology is less fashionable than molecular diagnostics, but it may be harder to replace. bioMérieux operates across blood culture, organism identification, antimicrobial susceptibility testing and laboratory automation.
Its advantage does not come from one isolated product. It comes from integrating several steps of the process: detect, identify, measure resistance and transmit the result. For a hospital laboratory, reliability, traceability and workflow continuity often matter more than the price of a single test.
4. Industrial Applications: testing before a failure costs millions
This activity serves food producers, pharmaceutical manufacturers, cosmetics groups and advanced-therapy companies. In regulated industries, an incorrect result can lead to a destroyed batch, a product recall or a halted production line. The cost of the test is small relative to the potential cost of failure.
Industrial Applications grew 9% in 2025, including 14% growth in pharmaceutical quality control. Accellix, acquired in 2026, adds rapid flow-cytometry solutions for cell and gene-therapy quality control.
| Growth engine | Current evidence | What needs confirmation |
|---|---|---|
| Non-respiratory BIOFIRE | +12% in the first nine months of 2026 | Sustainable growth above 8% |
| SPOTFIRE | +21% and more than 900 Q3 placements | Utilisation and reagent revenue per instrument |
| Microbiology | +6% in the first nine months | Improvement in China and margin progression |
| Industrial Applications | +8% in the first nine months | Pharma and advanced therapies |
Antimicrobial resistance is turning diagnostics into a necessity
Antimicrobial resistance is not a temporary investment theme. It is an intensifying constraint on healthcare systems.
According to the World Health Organization, approximately one in six laboratory-confirmed bacterial infections worldwide was resistant to antibiotics in 2023. Between 2018 and 2023, resistance increased in more than 40% of the pathogen–antibiotic combinations monitored. The problem is particularly serious where laboratories cannot identify the bacterium and its susceptibility to treatment quickly enough.
Empirical prescribing — giving an antibiotic before a precise diagnosis is available — may save time, but it can also lead to ineffective treatment and accelerate resistance. The economic and medical challenge is to shorten the interval between collecting a sample and choosing the right therapy.
This is exactly where bioMérieux operates: blood cultures, identification, susceptibility testing, molecular panels and data-management tools. The value is not limited to the number of tests sold. A faster diagnosis may shorten a hospital stay, prevent unnecessary antibiotic use and reduce transmission risk.
The WHO estimates that bacterial antimicrobial resistance was associated with 4.71 million deaths in 2021, including 1.14 million deaths directly attributable to resistance. At the current pace of action, treating resistant infections could cost $412bn annually by 2035, with another $443bn a year in productivity losses.
This does not automatically guarantee bioMérieux’s growth. Hospital budgets remain constrained, and countries with the greatest need sometimes have the least purchasing power. It does, however, strengthen the medical and regulatory necessity for rapid diagnostic systems.
A defensible lead, but not an invulnerable one
bioMérieux competes with much larger groups: Danaher through Cepheid, Roche, Abbott, Thermo Fisher and Qiagen. These companies possess considerable research capacity, commercial reach and financial resources.
bioMérieux’s protection comes from several overlapping layers:
- a large global installed base;
- long-standing laboratory relationships;
- a growing menu of tests;
- product-specific regulatory approvals;
- workflow integration;
- deep expertise in infectious diseases;
- research spending of approximately 12%–13% of revenue.
The group’s installed base expanded by 7% in 2025. That growth prepares future consumption but carries a cost. Instruments may be sold at modest margins or placed with customers to accelerate adoption. The return appears later if reagent volumes become sufficiently high.
The best leading indicator is therefore not the number of placements alone. It is the combination of new placements, reagent growth and gross-margin development.
R&D and approvals → installed instruments → laboratory integration → expanding test menu → recurring revenue → data and customer retention
Innovation: discipline or dispersion?
bioMérieux invests more heavily in research than many diagnostic companies. In the first half of 2026, R&D spending reached €257m, or 13.1% of revenue. Investment focused on molecular diagnostics, SPINCHIP and microbiology.
The company complements internal research with targeted acquisitions. SpinChip adds a rapid point-of-care immunoassay platform. Accellix strengthens quality control for cell and gene therapies. Neoprospecta contributes genomic capabilities for microbiological safety. Day Zero Diagnostics works on rapid pathogen identification.
The strategy appears financially disciplined: acquire relatively small technologies, avoid weakening the balance sheet and use bioMérieux’s global commercial network to bring them to market.
Innovation is never free, however. The partial impairment of VITEK REVEAL in 2025 showed that a promising technology can encounter technical or commercial difficulties. Pipeline quality must be assessed through approvals, sales and return on invested capital — not by the number of press releases.
SPINCHIP is now an important test. Its first high-sensitivity cardiac troponin assay has launched in Europe. The product brings bioMérieux into rapid cardiovascular diagnostics, but it must earn clinician trust against established competitors.
The €250m industrial bet
In May 2026, bioMérieux announced an investment of more than €250m to build a new BIOFIRE PCR-test manufacturing facility in France. The project is intended to reinforce European supply and create approximately 400 jobs over time.
The investment is consistent with the expansion of the installed base and the desire to improve supply-chain resilience. It also brings manufacturing capacity closer to European customers.
But it raises the standard the investment thesis must meet. If future growth remains close to 3%, the group could end up with excess capacity. Investors should monitor utilisation, capital expenditure, gross margin and return on invested capital.
Management must demonstrate not only that it can manufacture more, but that demand justifies the additional capacity.
Strong economics, with a distorted 2026
In 2025, bioMérieux reported:
- €4.07bn of revenue;
- 6.2% organic growth;
- €728m of contributive operating income before non-recurring items, or CEBIT;
- a 17.9% CEBIT margin;
- adjusted diluted earnings per share of €4.64;
- €462m of free cash flow.
The first half of 2026 was more difficult. Reported sales fell 3.9%, despite 0.2% organic growth, because of a weak respiratory season and an €87m negative currency effect. The CEBIT margin declined to 15.9%.
Free cash flow nevertheless reached €299m, an increase of 76%, and the company had €236m of net cash at the end of June. The balance sheet therefore allows bioMérieux to finance research, industrial investment and smaller acquisitions without aggressive leverage.
The third quarter changed the tone. Organic sales increased 8%; the GO•28 growth engines rose 13%; non-respiratory BIOFIRE grew 12%; SPOTFIRE rose 21%; microbiology increased 6%; and Industrial Applications advanced 8% over the first nine months. Respiratory panel sales declined 14% over the same period.
That is the most important signal of the year: the portfolio delivered strong growth without a favourable respiratory contribution.
Q3 2026: 8% organic growth despite a 14% decline in respiratory panels over the first nine months.
MITUXA interpretation: diversification is beginning to offset respiratory volatility.
Why the market remains sceptical
The strong third quarter does not remove the central weakness in the thesis: management reduced its medium-term ambitions.
The original GO•28 plan targeted approximately 7% annual sales growth from 2024 to 2028, at least 10% annual CEBIT growth and meaningful margin expansion. SPOTFIRE was expected to generate €450m of revenue in 2028.
In July 2026, bioMérieux lowered its 2027–2028 organic-growth ambition to a range of 3%–6%. CEBIT should still grow faster than revenue, but the earlier target of at least 10% has disappeared.
The revision suggests that China, currency movements, slower hospital instrument placements and product-launch timing are proving more difficult than anticipated. Consensus estimates point to roughly €4.15bn of revenue and €4.47 of adjusted earnings per share in 2026, followed by €4.38bn and approximately €4.8 per share in 2027.
The Mérieux family, through Institut Mérieux, controls approximately 59% of the company. This stability supports long-term industrial investment, but it reduces minority influence. It may also allow a scientific project to receive funding for longer before its financial return becomes evident.
Valuation: quality, but not yet a clear anomaly
At the €92.30 reference price, market capitalisation is approximately €10.9bn. After deducting net cash, enterprise value is close to €10.7bn.
On 2026 estimates, the shares trade at approximately 20.7 times adjusted earnings and around 11 times EBITDA. The free-cash-flow yield based on 2025 is approximately 4.2%.
This is not an excessive price for a diagnostic company with recurring revenue, a net-cash balance sheet and a leading infectious-disease franchise. It is not an obvious bargain either if organic growth settles near 3%–4%.
MITUXA scenarios to 2029
| Scenario | Core assumption | 2029 EPS | Multiple | 2029 value |
|---|---|---|---|---|
| Bear | Weak growth and continuing margin pressure | €4.70 | 16× | €75 |
| Base | Approximately 5% growth and margin recovery | €5.90 | 20× | €118 |
| Bull | Strong platform utilisation and operating leverage | €6.80 | 23× | €156 |
At €92.30, the base scenario offers an annualised return of approximately 9%–10%, including dividends. That is acceptable, but not sufficiently asymmetric for maximum conviction given the execution risks.
Decision zones
| Share price | MITUXA view |
|---|---|
| Above €110 | Demanding valuation |
| €90–€100 | Hold or monitor |
| €78–€85 | Progressive accumulation zone |
| Below €75 | Strong margin of safety if the thesis remains intact |
Catalysts
- non-respiratory growth above 8%;
- higher reagent revenue per SPOTFIRE instrument;
- additional regulatory approvals;
- successful SPINCHIP adoption;
- improvement in China;
- CEBIT margin returning towards 18%–19%;
- continued pharmaceutical quality-control growth;
- sustainable free cash flow above €500m.
What would invalidate the thesis
- organic growth below 3% for several quarters, excluding respiratory effects;
- SPOTFIRE placements without corresponding reagent growth;
- another reduction in the 2027–2028 outlook;
- a CEBIT margin remaining below 16%;
- higher capital expenditure without revenue or return-on-capital improvement;
- repeated impairments of acquired technologies;
- market-share losses in microbiology;
- a large, low-return acquisition financed with the existing cash position.
MITUXA Decision
bioMérieux is a high-quality company, but it is not a simple story. Its future does not depend on one flu season or one product. It depends on its ability to turn a growing installed base into recurring reagent consumption and then use that installed base to launch additional tests.
Antimicrobial resistance, point-of-care testing and the increasing complexity of pharmaceutical quality control are three supportive structural trends. The balance sheet protects the company during periods of investment and allows it to fund innovation without financial fragility.
The reduced medium-term targets nevertheless require discipline. The third quarter of 2026 is encouraging validation, not definitive proof. Reagent growth, margin recovery and the return on new manufacturing capacity still need to be demonstrated.
Verdict: POSITIVE WATCHLIST. Price trigger: below €85. Fundamental validation: GO•28 engines growing faster than the group, greater platform utilisation and a sustainable margin recovery.
The market is still watching the next respiratory season. Long-term investors should be watching the next decade of tests consumed by instruments that have already been installed.
Principal sources
- bioMérieux, Third-Quarter 2026 Business Review, 3 November 2026.
- bioMérieux, First-Half 2026 Results, 28 July 2026.
- bioMérieux, 2025 Financial Results, 27 February 2026.
- bioMérieux, Universal Registration Document 2025.
- World Health Organization, Global antibiotic resistance surveillance report 2025.
- World Health Organization, Landscape analysis of commercially available and pipeline in vitro diagnostics for bacterial priority pathogens, 2025.
This publication is independent research for information and educational purposes. It is not personalised financial advice or a recommendation to buy or sell securities. MITUXA estimates are scenarios, not guaranteed forecasts.
Questions: questions@mituxa.com